.png)

 Chat with us now!
 Send Email!
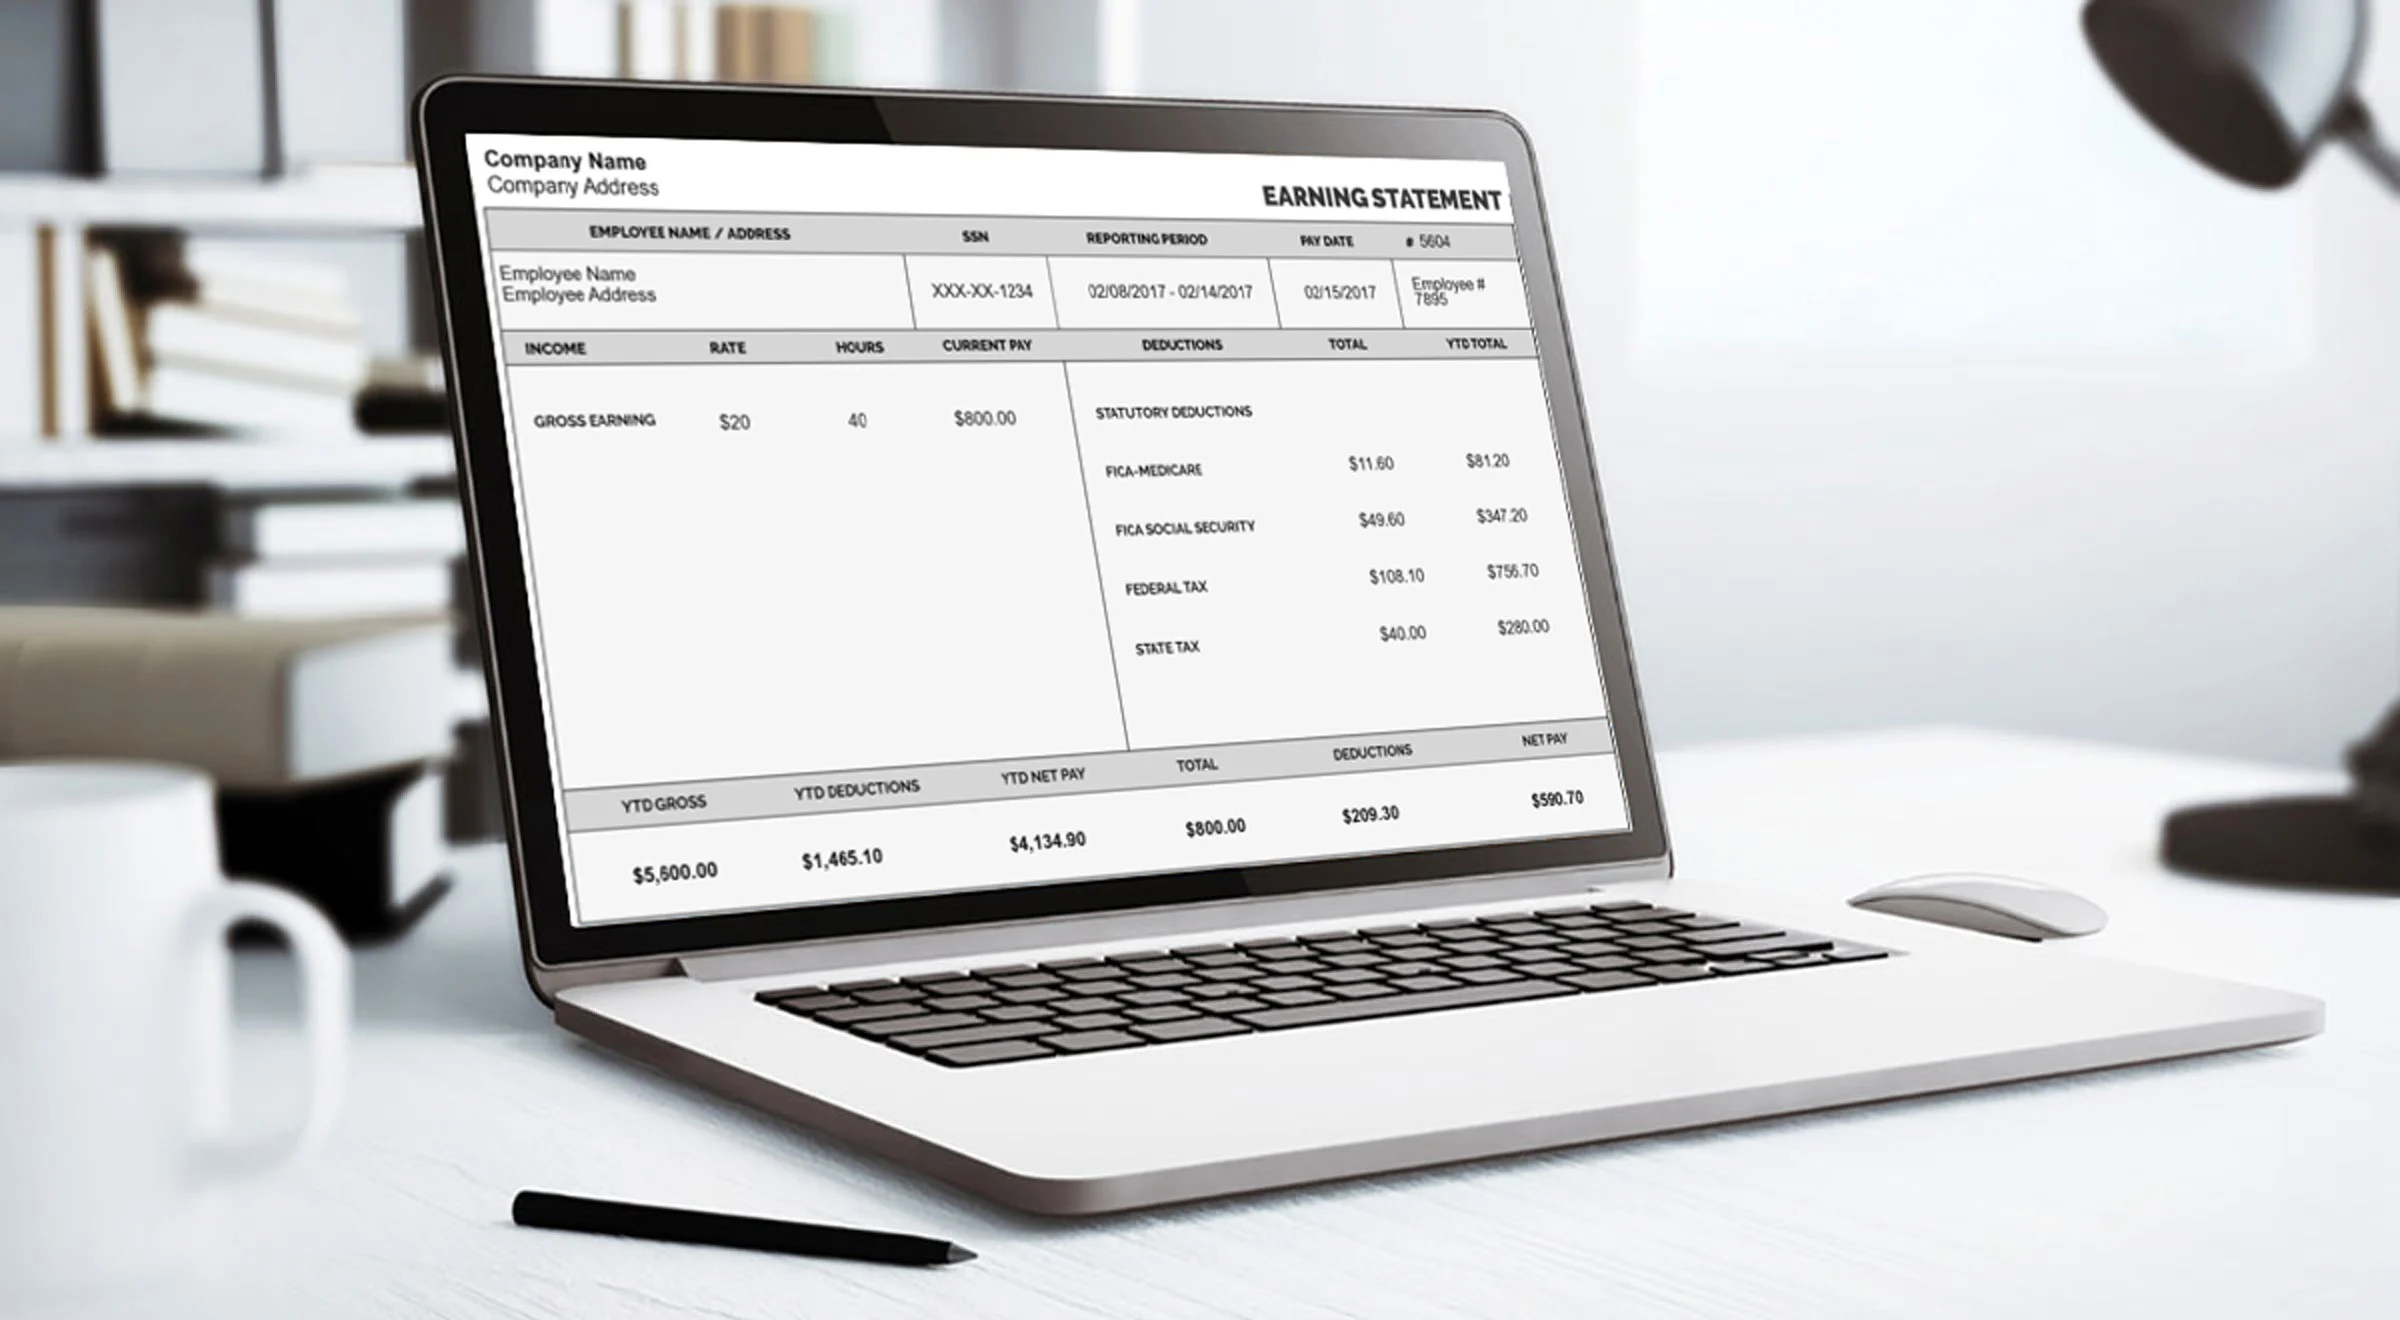
Social Security wages on a W2 are the earnings your employer reported on your W2 and can be found in Box 3.
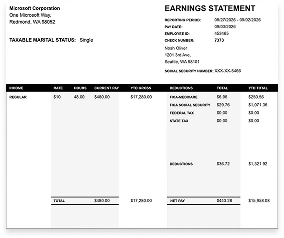
This article provides an overview of Social Security wages, as well as an explanation of any differences that may exist between wages and your regular wages. Your check stubs contain the same Social Security wages information, so whenever you see that figure in subsequent paychecks, you can simply add everything up to arrive at the answer.
Key Takeaways
- In a W-2, Social Security taxable wages are recorded in Box 3 to indicate how much one pays in the 6.2 percent tax that is required for Social Security.
- The taxable income for the year 2026 is $184,500, so the maximum amount that any employee could pay for Social Security tax is $11,439.
- The deferrals made to the 401k reduce the amount reported in Box 1 and appear in the original amount in Box 3; hence, the reason that Social Security wages are usually considered to be higher than wages in general.
- Health premiums that are paid before the tax is deducted through the cafeteria plan will get removed from both boxes.
- To arrive at the Social Security wages amount, a person needs to take the gross pay, deduct the amount that was deducted for the cafeteria plan, and then apply the tax of 6.2 percent.
- Even the tips reported are present in Box 7, Box 3 and Box 7 combined should not be more than the wage base amount.
What Are Social Security Wages?
Social Security wages refer to the wages on which you pay Social Security tax, which is statutory at 6.2%. If you have ever thought, “What are Social Security wages?” the answer is simple: Social Security wages are the wages used by your employer as the basis for evaluating and applying the Social Security tax to you.
The definition of Social Security wages is limited for a reason. Most types of income fall under Social Security wages, up to the annual FICA cap. Not all benefits are included, and whatever exceeds the cap is not counted. The employer deducts 6.2% from your paycheck and matches the amount for its own payments.
What Counts as Social Security Wages
The majority of your earnings have significance. The following are included in Social Security wages:
- Hourly pay and salary
- Commissions, bonus and overtime
- Paid time off, vacation, and paid sick leave
- Severance and holiday payments
- Retirement plan contributions such as (401(k)), 403(b) and 457(b) deferrals
- Value of Taxable fringe benefits, as well as premiums for group term life insurance coverage above $50,000
- Tips over $20 per month, which must be reported separately in Box 7.
Some pay is left out of the total:
- Health insurance premiums before taxes that were paid for in regard to a Section 125 cafeteria plan
- Payments regarding Health FSA and HSA from one’s salary
- Dependent care benefits irrespective of the annual limit
- Transit and parking benefits that comply with the law
- The contribution that the employer made to the matching retirement 401(k) plan for you
- Expenses incurred through the accountable plan for reimbursed business travel
- Insurance payouts for on-the-job injuries
- Any pay above the yearly wage base limit
Investment income, pensions, and rental income are not wages at all, so they never appear in Box 3. Your own 401(k) contributions are the item that surprises people most, and it explains most of the W2 questions covered below.
What is Social Security Wages on W2: Where to Find Box 3
In the W2 form, the box number that carries the information regarding Social Security wages is Box 3. While searching for the term W2 Box 3, many people compare Box 3 to other boxes. Here is a comparison between Social Security Box and all the other boxes:
- Box 1: Wages, tips, and other compensation; this is the income subject to federal taxes
- Box 3: Social Security wages
- Box 4: Amount of Social Security tax deducted, which is calculated as 6.2 % of Box 3 plus Box 7
- Box 5: Medicare wages and tips
- Box 6: Amount of Medicare tax deducted
- Box 7: Social Security tips
Box 3 is not essentially a copy of Box 1. Moreover, it does not reflect an individual’s gross wage. The reason behind searching for gross income on W2 and finding none is due to the fact that gross income is not mentioned anywhere in the boxes. Each box represents a specific type of tax and has its own condition with regard to the items it contains.
Wages vs Social Security Wages: What’s the Difference?
The difference between wages and Social Security wages comes down to which tax each number is built for. Box 1 is the base for federal income tax. Box 3 is the base for Social Security tax. Each one starts from your pay and then removes different items.
| W-2 box | Used for | Your 401(k) deferral removed? | Pre-tax health premium removed? | Capped? |
| Box 1 (wages) | Federal income tax | Yes | Yes | No |
| Box 3 (social security wages) | Social Security tax | No | Yes | Yes, $184,500 in 2026 |
| Box 5 (Medicare wages) | Medicare tax | No | Yes | No |
So when you compare wages vs. Social Security wages, remember that Box 1 can be smaller for two reasons: your retirement deferrals reduce it, and Box 3 does not follow that rule. For a closer look at the income tax side, check the blog of federal taxable income & FIT taxable wages on a paystub.
Why Are My Social Security Wages Higher Than Wages?
If you are asking why your Social Security wages are higher than wages, the most common cause is a 401(k). Pre-tax deferrals lower Box 1, but they stay in Box 3.
Take an employee earning $65,000 a year who puts 5% into a 401(k) and pays $2,400 a year in pre-tax health premiums:
- Box 1: $65,000 − $3,250 − $2,400 = $59,350
- Box 3: $65,000 − $2,400 = $62,600
- Box 4: $62,600 × 6.2% = $3,881.20
Box 3 is $3,250 higher than Box 1, which is exactly the 401(k) deferral. Nothing is wrong with the form.
The same thing happens with 403(b) and 457(b) deferrals: they reduce Box 1 but stay in Box 3.
The opposite can also happen. If you earned more than the wage base in a year, Box 3 stops at the cap while Box 1 keeps climbing. If your numbers do not fit either pattern, ask your payroll team to check the form before you file.
How to Calculate Social Security Wages?
If you want to know how to calculate Social Security wages from your own pay stub, follow these steps:
- Start with gross pay for the pay period.
- Subtract Section 125 cafeteria-plan deductions, such as pre-tax health insurance, FSA, HSA and dependent care contributions.
- Do not subtract 401(k), 403(b) or 457(b) deferrals.
- Stop counting once year-to-date pay reaches the wage base ($184,500 in 2026).
- Multiply the result by 6.2% to get the Social Security tax.
Example: A biweekly pay stub shows $2,500 in gross pay, $100 in pre-tax medical premiums, and a $125 401(k) deferral.
- Social Security wages: $2,500 − $100 = $2,400
- Social Security tax withheld: $2,400 × 6.2% = $148.80
- Local Income tax wages for the same period: $2,500 − $100 − $125 = $2,275
At year-end, add up gross pay and before-tax benefit deductions from your final stub. The result should match Box 3 on your W-2. If it does not, compare your year-to-date figures with the form, and see our guide on getting a W-2 from a previous employer if you need a copy of the form.
Social Security Tips on W2
What are social security tips on W2? It is Box 7, and it shows the tips you reported to your employer that are subject to Social Security tax. Social Security tips on W2 are kept apart from Box 3 so the form shows wages and tips as two separate lines.
Tips are included once you report $20 or more in a month at one job. That covers cash tips, card tips, and your share of any tip pool, under the Internal Revenue Service tip reporting rules. Box 4 should equal 6.2% of Box 3 and Box 7 combined, and the two boxes together cannot go past the yearly wage base. The W2 Social Security tips you report also count toward your future benefits, so reporting them accurately matters.
FICA Cap and FICA Rate for 2026
The maximum amount on which taxes can be levied for Social Security during a fiscal year is provided for under the Federal Insurance Contributions Act (FICA) limit. For the year 2026, this amount has been set at $184,500 after increasing from $176,100 for 2025, according to figures obtained from the AARP and the SSA wage base table. According to AARP, the limit for 2027 is $192,300. Social Security tax withholding stops for the remaining portion of the year once wages for Box 3 reach the limit referred to above.
The FICA rate 2026 is unchanged from last year:
| Tax | Employee rate | Employer rate | 2026 limit |
| Social Security Tax Rate | 6.2% | 6.2% | $184,500 |
| Medicare Tax Withheld | 1.45% | 1.45% | None |
| Additional Medicare Tax Rate | 0.9% | None | Applies to wages above $200,000 |
In 2026, the highest amount allocated for Social Security tax by any individual employee stands at 11,439(184,500 at an employee tax rate of 6.2%), whereas the employer shares the exact amount of Social Security Tax.
The Medicare tax continues for every dollar made as a salary. It should be noted that the Social Security tax limit is applicable for each employee separately, meaning that two jobs can lead to a situation whereby one employee has a combined Social Security tax surpassing the stipulated limit.
Conclusion
The amount regarding Social Security wages reported to your salary excludes pre-tax deductions and amounts up to $184,500 for 2026. The payroll deductions for your 401(k) contributions are not included in this total, which is why there is usually a discrepancy between Box 1 and Box 3. Recognizing the formula for boxes makes it less complicated to identify mistakes in them.
Would you like to have all tax deductions listed distinctly? The StubCreator can generate stubs showing wages, withholdings, and deductions, making it possible to compare your stub to W2 and make corrections.