.png)

 Chat with us now!
 Send Email!
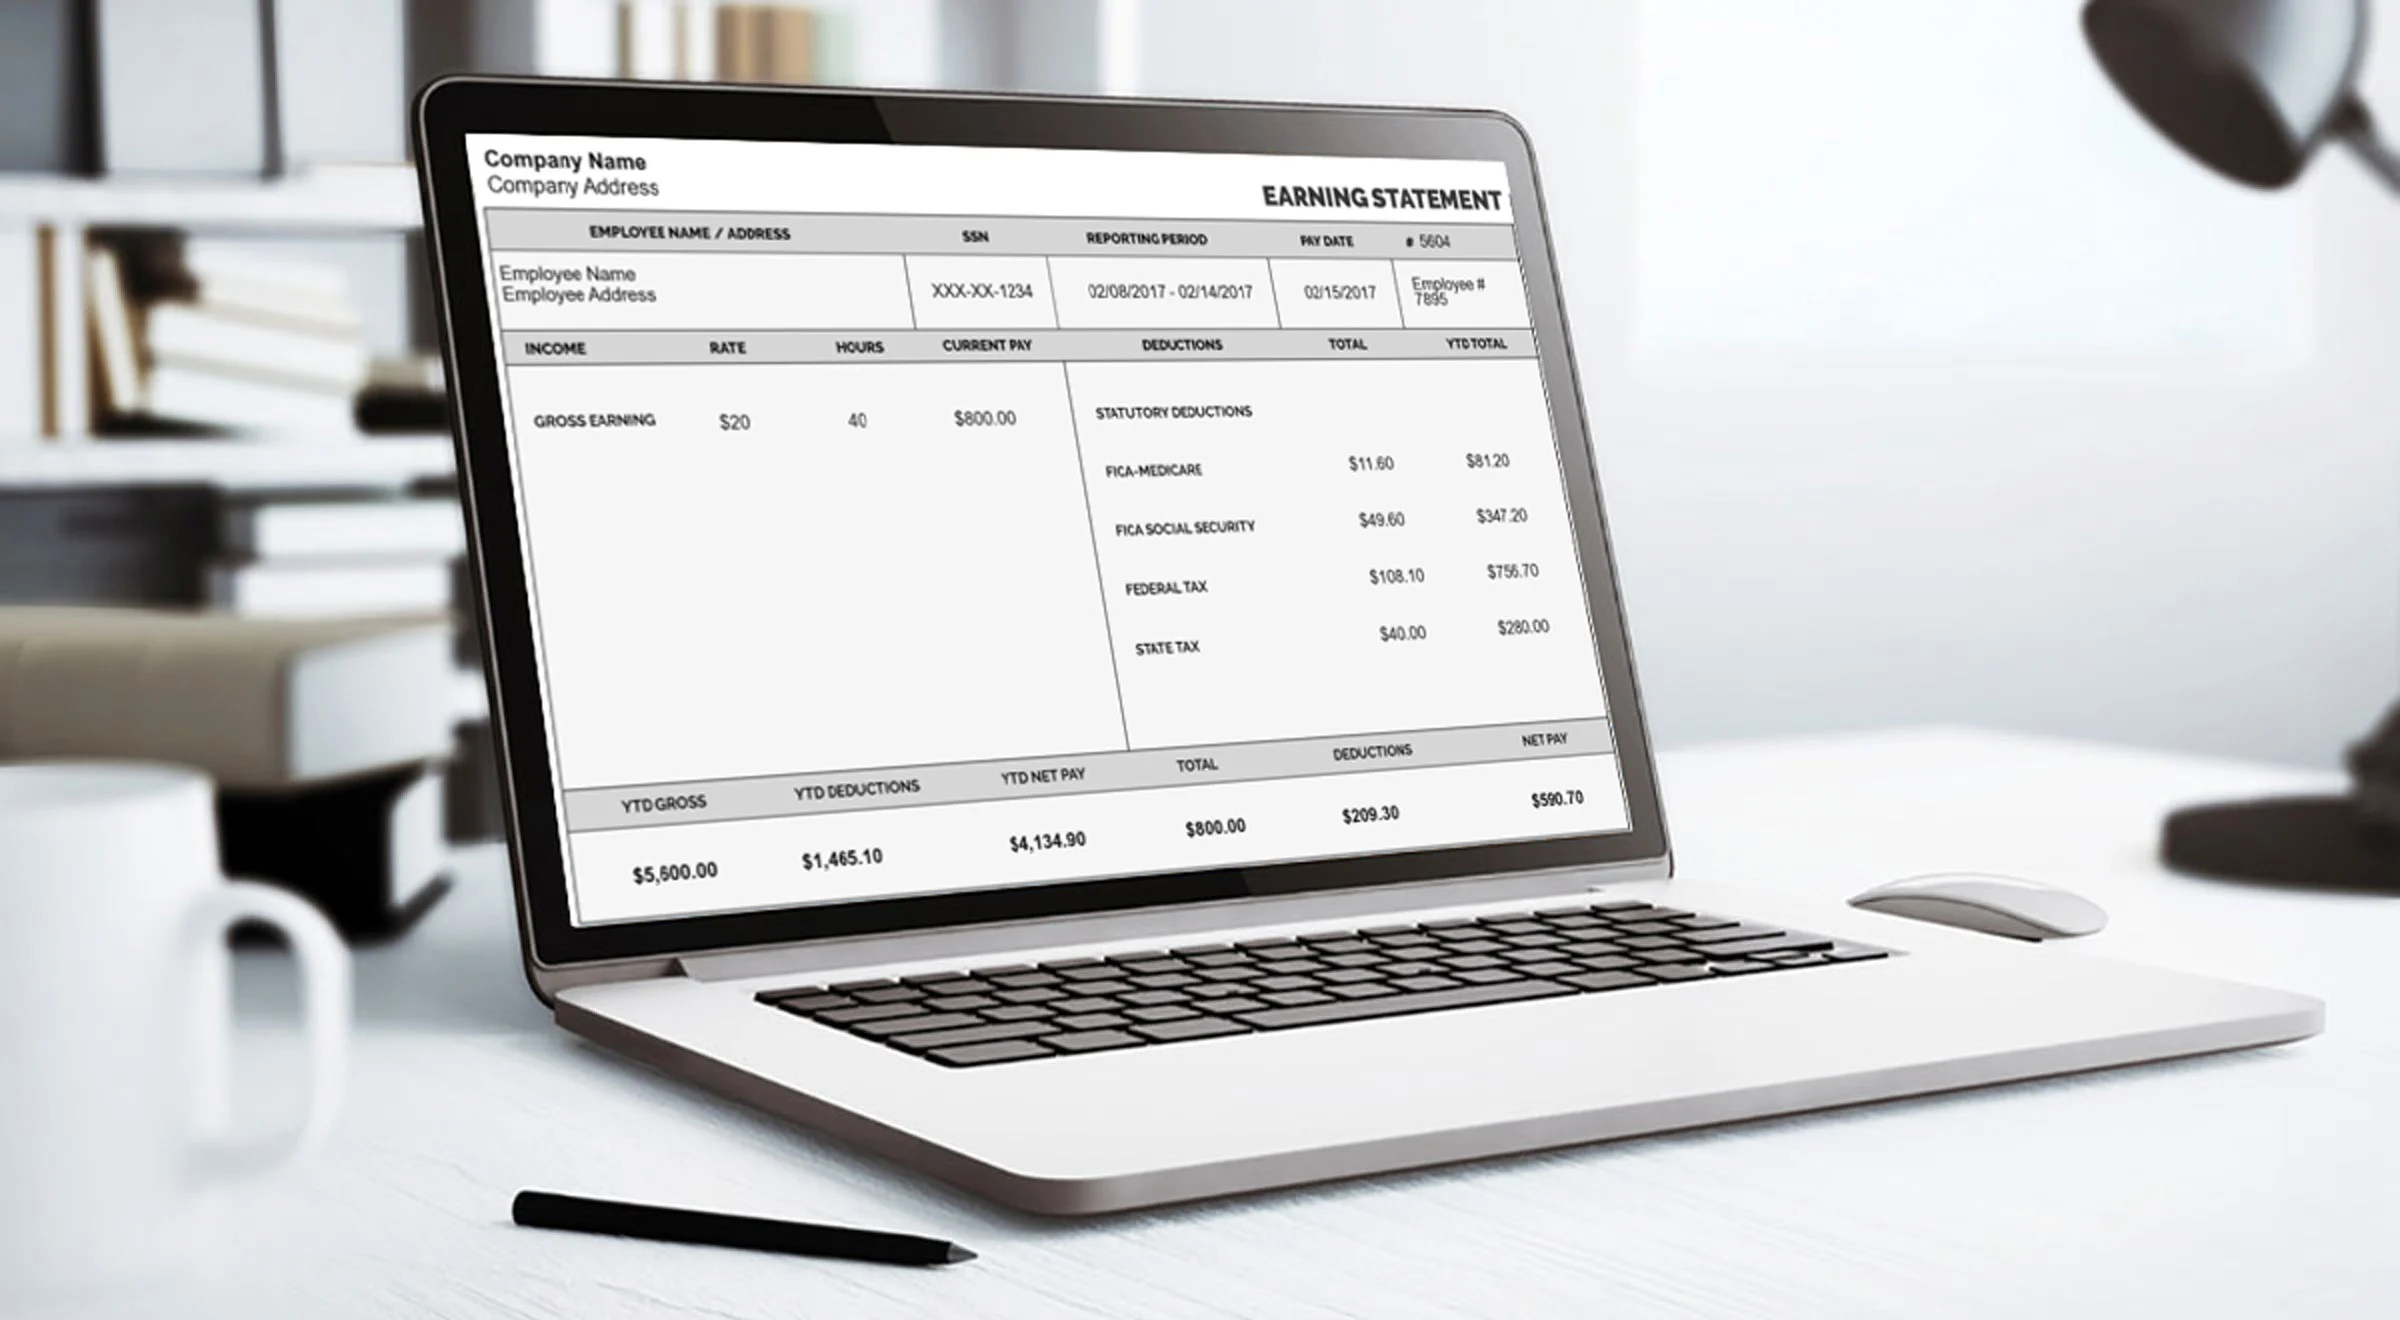
Payroll terms can often look confusing, especially when they affect your take-home pay or taxable income.
When you look at your check stubs, you probably have some doubts regarding earnings and deductions that are attached to your earnings and benefits. GTL (Group Term Life Insurance) could be one such deduction. When you find GTL on paycheck, it refers to the life insurance coverage that has been offered as part of an employer benefits package.
This kind of life insurance coverage is typically available either free of charge or for a low cost. Nevertheless, depending on how much coverage is offered, a part of it could be deemed taxable income by the IRS and included as imputed income in your paycheck or W-2. For this reason, it’s very important to know exactly “what is GTL on paystub” for proper tax reporting and payroll processing.
In this article, we’ll explain how GTL is determined and what it represents for you so that you can better understand its importance regarding taxable income. We will also describe how it influences your employee’s income for taxation and why it is included in your payroll information.
Key Takeaways
- GTL means Group Term Life Insurance-an employer-provided life insurance benefit.
- If the coverage exceeds $50,000, it will become taxable income, according to the IRS rules.
- The cost for GTL is set according to age brackets using IRS uniform premium tables.
- GTL imputed income will show in Box 12, Code C, on your Form W-2.
- The cost increases starting at ages 45, 55, and 65.
GTL Meaning in Payroll
GTL from payroll stands for Group Term Life insurance, which is a benefit provided to employees by the employer to cover them for a fixed duration of time or period during which they are working.
GTL is part of an employee benefits programme aimed at providing security to the employee and his family members. If the employee dies during the period of coverage, the insurance policy will provide the death benefits to beneficiaries mentioned in the policy.
GTL can also be seen on the paycheck or pay stub. This refers to the cost incurred by the employer for providing insurance coverage. If the income exceeds the limit of coverage set by the IRS, then the value exceeding the limit will be taxed and added to the taxable wages of the employee.
What is GTL on pay stub?
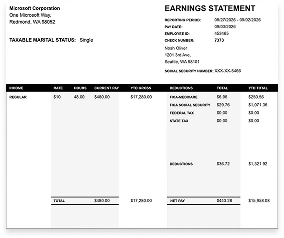
GTL on pay stub stands for Group Term Life insurance in excess of $50,000 provided by your employer that is subject to imputed income reporting under IRS rules.
The taxable GTL paystub figure shown on your paycheck is in accordance with IRC Section 79 and IRS Publication 15-B. It does not come off your earnings but instead is additional taxable income, which means that it is included in your earnings for tax matching purposes.
The term itself might be different based on the payroll system used by your employer. Instead of GTL, it can appear as GTLI, GROUP LIF, GL50K+, and LIFE IMP. Whatever term is used, it always stands for Group Term Life.
GTL works on a “group” basis, which covers all eligible employees within one plan. Most employers offer coverage worth one or two times an employee’s annual salary; the exact figure can vary by organization. Some employees also choose to purchase additional coverage at their own cost for further protection.
Tip: Before finalizing your records, you can use a paystub template to preview how your information should appear. This ensures all your data is accurate and professional before you submit it for official use.
How Does Group Term Life Insurance Work?
When the employee dies while insured under the group plan, Group Term Life Insurance will provide a death benefit for the employee’s beneficiaries. The amount of coverage offered is usually 1-2 times the employee’s gross salary and provided to him/her at no cost.
In contrast with individual life insurance, GTL normally does not require any medical examinations. This form of coverage is called guaranteed issue as qualified employees can get it regardless of their health status.
The insurance coverage usually expires once the employee leaves the job. Some companies give the option of turning the group term life insurance into an individual or whole life policy.
It is also necessary to review the list of your beneficiaries regularly in case of a significant life event, such as marriage or birth of a child. If the organization where you work has a spouse protection program, make sure to understand all the terms of this offer.
GTL Imputed Income and Taxable Fringe Benefits
Group Term Life Insurance (GTL) is often considered a taxable fringe benefit when the coverage provided by your employer exceeds $50,000.
The employer usually pays the premium for this additional coverage, but its value is reported as imputed income by the IRS. This means the value of that excess coverage is included in the employee’s taxable wages, but the employee doesn’t actually receive that amount as a tangible cash benefit on their paycheck. You may see this on your paystub as GTL imputed income which is a minor increase in the taxes withheld from your earnings.
In many cases, the employer pays the premium for this extra coverage, but the IRS still treats the value of that benefit as imputed income.
There are some GTL benefits you can check below:
- Offers monetary protection for your dependents upon your death
- Most immediate coverage without a medical exam
- Workplace coverage with little or no cost to employees
- The premiums tend to be cheaper than stand-alone life insurance policies
- Simple enrollment with your employer
- Possibly transferable or convertible after separating from the employer
- Provides assurance that your family has a minimum level of financial security
Employers are responsible for reporting imputed income on employee pay stubs and annual tax forms like the W2. This ensures the taxable fringe benefit is properly included in total wages for federal income tax, Social Security, and Medicare purposes.
Limitations of GTL to keep in mind:
- You’ll find that most coverage stops once you leave employment.
- Benefits are also limited for family members.
- Finally, if you’re older, you may find your costs are higher.
Taking a good look at your GTL details during open enrollment is a good way to ensure that it meets all your needs.
Is GTL Considered Taxable Income?
Under U.S. tax law, GTL (Group Term Life Insurance) provided by your employer may constitute taxable income depending on its amount. The IRS has specific rules as to when GTL becomes taxable income.
GTL Coverage Up to $50,000 Is Not Taxable
As per the Group Term Life Insurance on W2 that refers, employees receiving employer-provided group term life insurance with an employer contribution of $50,000 or less qualify for tax-free treatment; that means no federal income tax, Social Security tax, or Medicare tax is payable on this portion.
GTL Insurance Coverage Over $50,000 Is Taxable
If the coverage exceeds 50,000 of group term life insurance coverage for you and/or your dependents, the IRS requires the value of this additional coverage to be included as income, known as imputed income.
Though not in cash form, the IRS considers your benefit to be compensation and thus must tax it accordingly.
IRC Section 79 gives the IRS a de minimis benefit threshold of $50,000, which remains the same till 2026. Any taxable amount above that limit falls subject to the FICA taxes (Social Security and Medicare). Though this cost is shown in your taxable wages on the W-2, your employer is generally not obliged to withhold federal income taxes on this non-cash benefit.
Spouse or dependent coverage is treated differently. If the cost is over $2,000, it is taxable.
To illustrate, if your workplace insurance policy is $100,000, the first $50,000 is tax-exempt. But the other $50,000 is considered GTL imputed income calculated based on your age and the IRS premium table.
How Does the IRS Calculate the Taxable Amount?
The IRS uses an official table based on age (Uniform IRS Premium Table I) to determine insurance benefits and calculate their taxable GTL value. GTL amount is determined based on multiple variables including:
- Age Group & Coverage Amount
- Amount exceeding the $50,000 tax-exempt limit
As you get older, you will have to pay a higher IRS premium on each $1,000 of coverage provided.
Does Group Life Insurance Affect My Paycheck?
Yes, but indirectly. The GTL amount reflected on your pay stub should not be considered an itemized deduction from your paycheck.
- Your wages will then have slightly increased federal, state, Social Security and Medicare tax withholdings.
- Your take-home pay may decrease slightly due to increased taxes incurred as a result of GTL deductions, rather than as a direct result of GTL itself.
IRS Premium Table
| GTL Coverage Amount | Taxable? | IRS Rule |
| $0 – $50,000 | No | Fully tax-exempt |
| Above $50,000 | Yes | Taxable as “imputed income.” |
The IRS uniform premium table sets the monthly cost per $1,000 of coverage above $50,000. Your age bracket decides the rate:
| Age Bracket | Cost per $1,000 per Month |
| Under 25 | $0.05 |
| 25–29 | $0.06 |
| 30–34 | $0.08 |
| 35–39 | $0.09 |
| 40–44 | $0.10 |
| 45–49 | $0.15 |
| 50–54 | $0.23 |
| 55–59 | $0.43 |
| 60–64 | $0.66 |
| 65–69 | $1.27 |
| 70 and above | $2.06 |
How to Calculate GTL Imputed Income
Below is the formula to calculate GTL imputed income.
-> [(Coverage amount − $50,000) ÷ 1,000] × IRS monthly rate × 12 months
Example: A 45-year-old person has $150,000 in coverage, and thus the excess coverage is $100,000. The rate charged is $0.15 per $1,000 per month, resulting in $100 x $0.15 x 12 = $180 in annual imputed income.
Here are the steps to verify the GTL amount on the pay stub:
- Determine the amount of coverage from the HR department.
- Then deduct $50,000 from the coverage amount.
- Next, divide the result by 1,000.
- Then multiply the result by the rate applicable to your age group.
- Finally, multiply it by 12 and see if it matches the GTL value on your pay stub.
How GTL Is Reported on Your W2
The inclusion of GTL earnings can be found in various places on Form W2. The total GTL would have already been incorporated in Boxes 1, 3, and 5 as part of your total taxable earnings. Moreover, the total GTL sum also shows up in Box 12 under Code C on the same form.
Before you submit your tax return, check your pay stub from the end of December on the annual W-2 report. The total GTL at the end of the year on the pay stub should be the same as shown under Box 12, Code C on the W2.
Why GTL Appears on Your Pay Stub?
The Group Term Life on your paycheck is there because your employer offers you Group Term Life Insurance coverage, and because the IRS requires any taxable portion of it to be reported as income.
Once coverage goes over this amount, though, its value is taxable and appears on your pay stub as the “imputed cost.” Instead of being automatically withheld from your paycheck as it is for deductions removed from wages paid, employers simply add it on, so payroll taxes can be calculated accurately.
This ensures that their benefits tracking tools will not hide income and affect withhold federal income tax. It provides clarity for you:
- How much GTL coverage do I currently have?
- Check if any portion of your coverage is taxable
- How it affects your gross and taxable wages
GTL on paycheck to maintain accurate payroll records and to comply with IRS rules regarding employer-provided life insurance benefits.
How to Read GTL On Paycheck Stub?
Understanding GTL paystub may seem complex at first, but once you know where to look, it becomes much simpler.
GTL represents the taxable value of life insurance coverage provided by your employer.
First and foremost, you must understand that GTL does not constitute a deduction taken out of your paycheck; rather, it represents the imputed cost of life insurance provided by your employer that exceeds $50,000, and that must be reported as income by them to the IRS.
Conclusion
With this knowledge of what GTL stands for on a pay stub in mind, you can now quickly review your paycheck. And if you ever have to create one yourself, then either come back to this article or use a reliable paystub generator – that will work too.